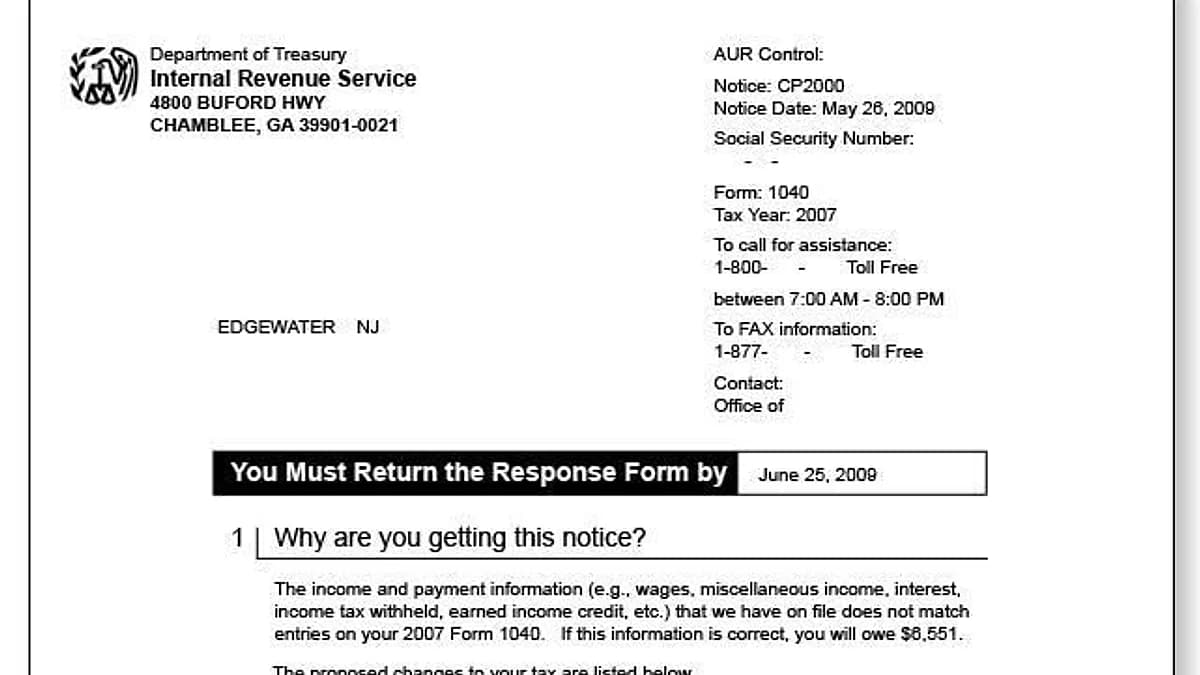
What Is an IRS CP2000 Notice?
A CP2000 is a proposed adjustment issued through the IRS Automated Underreporter process when information supplied by employers, banks, brokers or other payers does not appear to match a filed return. It is not itself an audit notice or a bill. Taxpayers can agree, disagree, or agree in part.
Third-party records may include Forms W-2, 1099-NEC, 1099-INT, 1099-B and 1099-R. A discrepancy does not prove that the IRS calculation is correct.
Why Did You Receive a CP2000?
Missing or mismatched Form 1099 income
Freelancers may omit income or report the same payment within a larger gross receipts figure that the matching process does not recognize. Reconcile the reported amount rather than automatically accepting additional income.
Stock sales and missing cost basis
Broker-reported proceeds can substantially exceed taxable gains. For example, $80,000 of sale proceeds and $72,000 of basis generally produces an $8,000 gain before other adjustments, not $80,000 of gain.
Duplicate forms or incorrect payer information
A corrected 1099, duplicate reporting, or a reporting error can explain a mismatch. Collect evidence and request corrections from the payer where appropriate.
Retirement distributions and tax credits
A Form 1099-R may reflect a rollover or partly taxable distribution. Other notices can involve credits or withholding discrepancies.
How to Respond to an IRS CP2000 Notice
- 1Authenticate and read the noticeCheck the tax year, proposed changes and reply instructions. Verify unfamiliar correspondence using IRS.gov rather than links in unsolicited messages.
- 2Compare records with your filed returnReview Forms W-2 and 1099, investment basis, business receipts, expenses, withholding and estimated payments.
- 3Decide whether to agree, disagree or agree in partIf you disagree, explain each contested item and attach a concise reconciliation and relevant documents. If you agree, follow the notice response instructions.
- 4Respond by the date on your noticeCP2000 letters commonly allow 30 days, or 60 days for addresses outside the United States, but rely on your actual notice. Follow the specified mail, fax or upload process and retain proof of submission.
What Documents Support a CP2000 Dispute?
- Filed federal return and schedules
- Original and corrected Forms W-2 and 1099
- Brokerage statements and cost-basis records
- Bank statements and bookkeeping reports
- Invoices, expense receipts and payment records
- A line-by-line explanation linking evidence to each proposed adjustment
Books out of date? Our bookkeeping services can help reconcile the records behind your response.
Should You File Form 1040-X?
Do not automatically file an amended return solely because a CP2000 arrived. The IRS usually instructs you to respond to the notice; if other changes to the same year are necessary, follow the applicable instructions regarding Form 1040-X. Uncoordinated filings can complicate resolution.
What Happens if You Ignore the Notice?
The IRS may continue the proposed assessment process and issue a statutory notice of deficiency, such as CP3219A. That later notice carries distinct Tax Court petition rights and deadlines. Do not confuse its deadline with the CP2000 reply period. Proposed tax may also include interest or applicable penalties.
If the proposed tax is later assessed and you receive a balance-due notice, see our IRS CP14 notice guide, or look up other letters in our IRS notices library.
When Attorney-Led CP2000 Help Makes Sense
Substantial adjustments, multiple tax years, complex securities transactions, incomplete books, penalty disputes or a statutory notice of deficiency warrant careful review. Every tax resolution case at Valoria Consulting is handled by our tax attorney; the firm coordinates accounting records and notice-response preparation as appropriate.
Learn more about our IRS tax resolution services.
Frequently Asked Questions
Is a CP2000 an audit?
No. It is generally a proposed adjustment based on information matching, not a formal audit notice.
Does it mean fraud?
No. A mismatch alone does not establish fraud.
Can I dispute the amount?
Yes. Respond with explanations and supporting evidence before the stated deadline.
Must I pay immediately?
A CP2000 is a proposal, not itself a bill. Verify and respond before accepting an amount.
Related Guides and Services
Authoritative References
- IRS — Understanding your CP2000 series notice (opens in a new tab)
- IRS — Topic no. 652, Notice of underreported income – CP2000 (opens in a new tab)
- Taxpayer Advocate Service — Notice CP2000 (opens in a new tab)
- IRS — Publication 5181 (PDF) (opens in a new tab)
General educational information. Notice-specific deadlines and IRS procedures can change; always rely on the exact notice you received. No outcome is guaranteed. References checked October 30, 2026.
Get Attorney-Led IRS Notice Assistance
If you received a CP2000, Valoria Consulting can review the proposed changes and develop an evidence-based response strategy. Every tax resolution case is handled by our tax attorney, without a guaranteed outcome.